
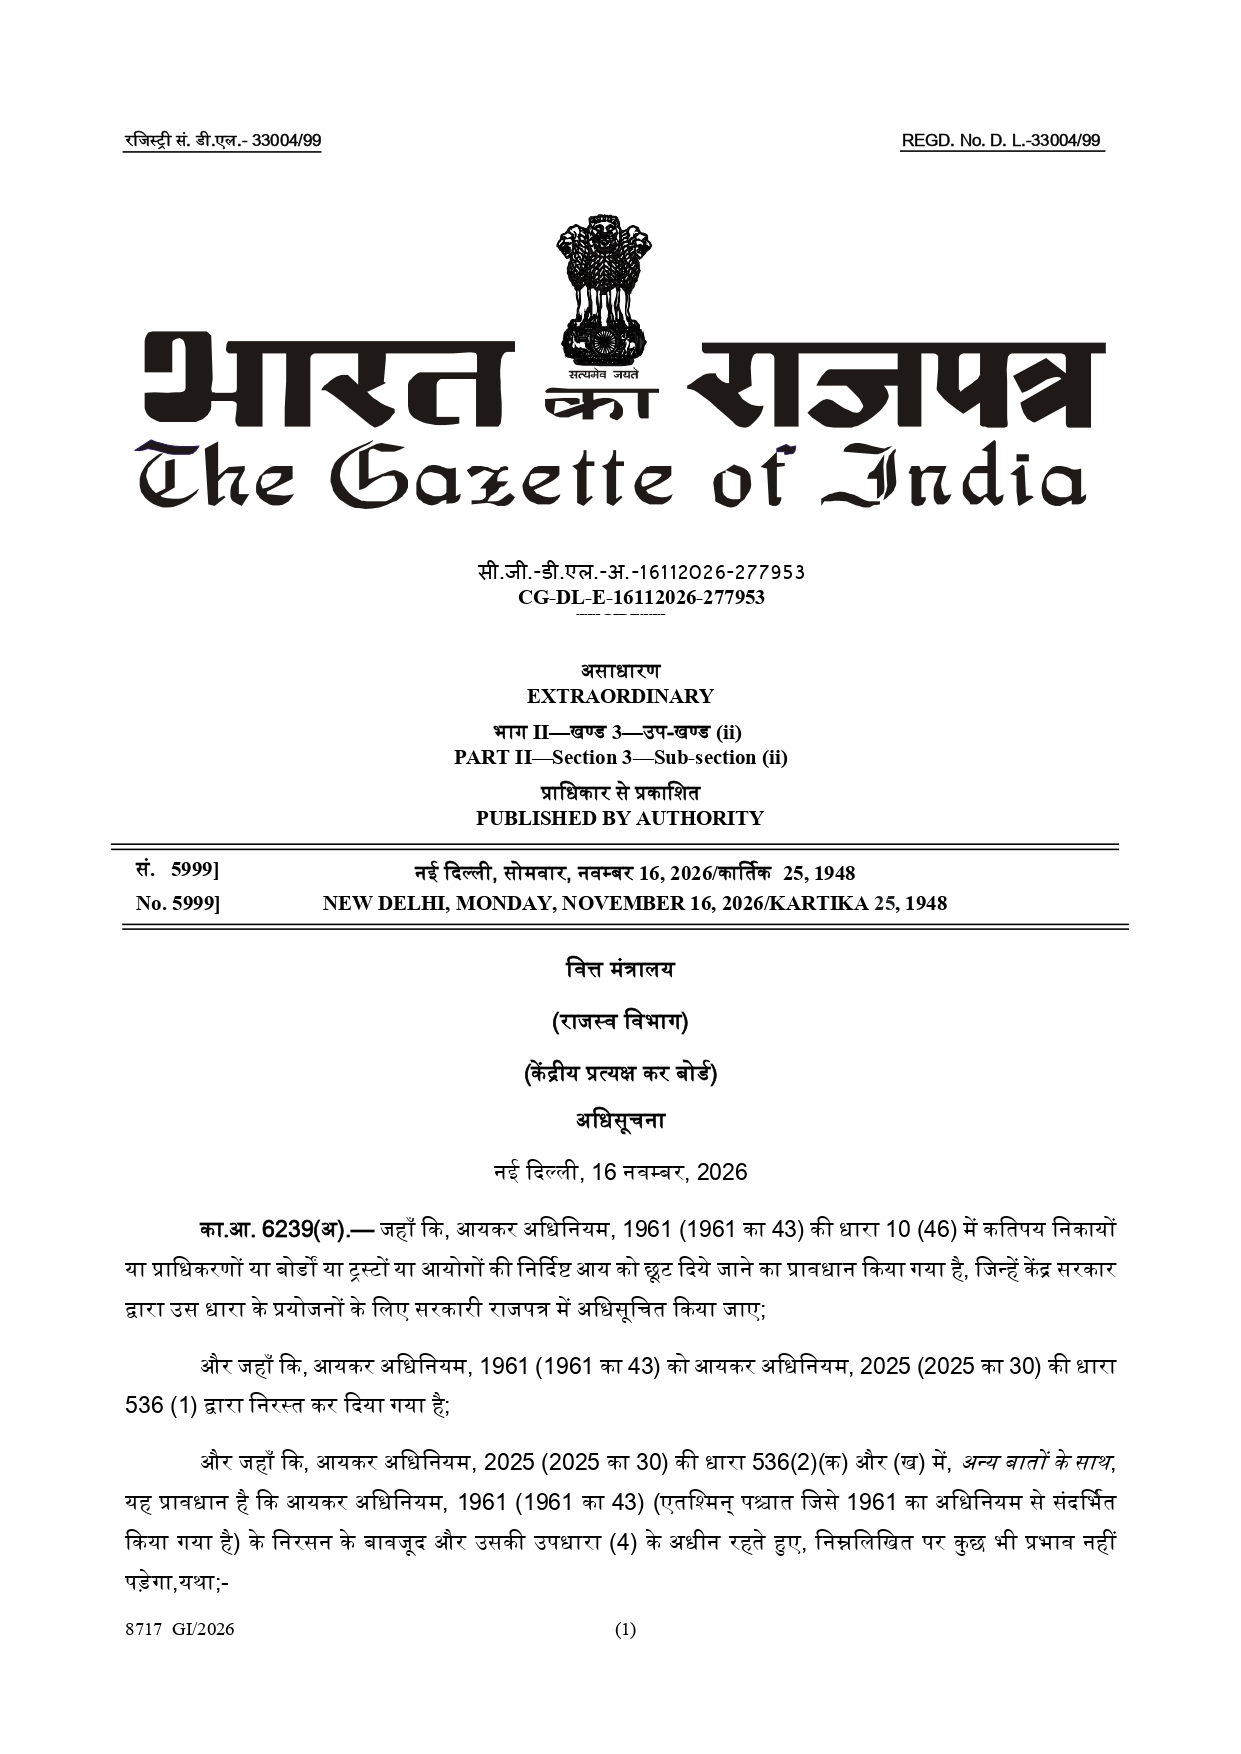
Income Tax Exemption Granted to Joint Plant Committee Under Section 10(46) for FY 2022-23 to 2025-26
केंद्र सरकार ने अधिसूचना संख्या S.O. 6239(E) के माध्यम से जॉइंट प्लांट कमेटी (PAN: AAAJJ0197P) को आयकर अधिनियम, 1961 की धारा 10(46) के अंतर्गत निर्दिष्ट आय पर आयकर छूट प्रदान की है।
अधिसूचना के अनुसार, कमेटी की निम्नलिखित आय को छूट के दायरे में शामिल किया गया है—
- जर्नल की सदस्यता तथा डेटा संकलन, प्रकाशन एवं ट्रांसमिशन से प्राप्त आय।
- टाटा स्टील लिमिटेड और SAIL से प्राप्त होने वाला ब्याज।
- मुंबई, नई दिल्ली एवं कोलकाता स्थित ट्रांजिट हाउस से प्राप्त यूटिलिटी चार्ज।
- फिक्स्ड डिपॉजिट, सरकारी प्रतिभूतियों एवं सरकारी बॉन्ड से प्राप्त ब्याज आय।
छूट की प्रमुख शर्तें: कमेटी किसी भी व्यावसायिक गतिविधि में संलग्न नहीं होगी। उसकी गतिविधियों एवं निर्दिष्ट आय की प्रकृति में कोई बदलाव नहीं होना चाहिए तथा उसे आयकर अधिनियम, 1961 की धारा 139(4C)(g) के तहत आयकर रिटर्न दाखिल करना अनिवार्य होगा।
इन शर्तों का उल्लंघन होने पर दंडात्मक कार्रवाई के साथ आयकर छूट वापस ली जा सकती है।
प्रभावी अवधि: यह अधिसूचना पूर्वव्यापी प्रभाव से वित्तीय वर्ष 2022-23 से 2025-26 (निर्धारण वर्ष 2023-24 से 2026-27) तक लागू होगी।
इस प्रकार, जॉइंट प्लांट कमेटी को निर्धारित शर्तों के अनुपालन के अधीन उसकी निर्दिष्ट आय पर आयकर छूट का लाभ मिलेगा।
MINISTRY OF FINANCE
(Department of Revenue)
(CENTRAL BOARD OF DIRECT TAXES)
NOTIFICATION
New Delhi, the 16th November, 2026
S.O. 6239(E).— Whereas, section 10 (46) of the Income-tax Act, 1961 (43 of 1961) provided for exemption of specified income of certain bodies or authorities or Boards or Trusts or Commissions as may be notified by the Central Government in the Official Gazette for the purposes of that section;
And whereas, the Income-tax Act, 1961 (43 of 1961) was repealed by section 536 (1) of the Income-tax Act, 2025 (30 of 2025);
And whereas, section 536(2)(a) and (b) of the Income-tax Act, 2025 (30 of 2025), inter alia, provides that irrespective of the repeal of the Income-tax Act, 1961 (43 of 1961) (hereinafter referred to as the Act of 1961) and subject to sub-section (4) thereof, nothing shall affect-
(i) the previous operation of the provisions of the Act of 1961 and any order or anything duly done or suffered thereunder; or
(ii) any right, privilege, obligation or liability acquired, accrued or incurred under the Act of 1961 or orders under that Act;
And whereas, section 536(2)(c) of the Income-tax Act, 2025 (30 of 2025) provides that the provisions of the Act of 1961 shall continue to apply to any proceeding pending on the date of commencement of the Income-tax Act, 2025 (30 of 2025) and to any proceedings initiated on or after the 1st April, 2026 (including notices, assessment, reassessment, recomputation, rectification, penalty, reference, revision and appeals) in respect of any tax year beginning before the 1st April, 2026 and such proceedings shall be carried out as per the procedure specified in the Act of 1961;
And whereas, section 536(2)(e) of the Income-tax Act, 2025 (30 of 2025) provides that any proceeding pending on the date of its commencement before any income-tax authority or any other authority constituted under the repealed Income-tax Act, Appellate Tribunal, or any court, by way of application, appeal, reference or revision or by any other means, shall be continued and disposed of as if this Act had not been enacted;
Now, therefore, in pursuance of the provisions of section 536(2)(a) to (c) and (e) of the Income-tax Act, 2025 (30 of 2025), the Central Government hereby notifies, for the purposes of section 10 (46) of the Act of 1961, “Joint Plant Committee (PAN:AAAJJ0197P)”, a Body constituted by the Central Government, in respect of the following specified income arising to that body, namely:-
(a) receipts from subscriptions to journals published by Joint Plant Committee and other similar receipts generated from compilation and publication of data, data transmission;
(b) interest due and payable from Tata Steel Ltd. and SAIL;
(c) utility charges from transit houses of Joint Plant Committee located at Mumbai, New Delhi and Kolkata;and
(d) interest income from Fixed Deposits, Government Securities and Government Bonds.
2. This notification shall be effective subject to the conditions that Joint Plant Committee (PAN:AAAJJ0197P)–
- (a) shall not engage in any commercial activity;
- (b) its activities and the nature of the specified income shall remain unchanged throughout the financial years; and
- (c) shall file return of income in accordance with the provisions of 139(4C)(g) of the Act of 1961.
3. Failure to comply with these conditions shall result in the initiation of penal actions under the provisions of the Act of 1961, and withdrawal of exemption granted u/s 10(46) of the Act of 1961.
4. This notification shall be deemed to have been applied for financial years 2022-23, 2023-24, 2024-25 and 2025- 26 relevant to assessment years 2023-24, 2024-25, 2025-26 and 2026-27.
[Notification No. 142 /2026/ F.No.300196/15/2025-ITA-I]
HARDEV SINGH, Under Secy.
Source: Click here to view/download PDF
नोट :- हमारे वेबसाइट indiangovtscheme.com पर ऐसी जानकारी रोजाना आती रहती है, तो आप ऐसी ही सरकारी योजनाओं की जानकारी पाने के लिए हमारे वेबसाइट indiangovtscheme.com से जुड़े रहे।